In this article
A roofing sales rep’s cost includes compensation, employer burden, leads and support. Separate recurring cost from one-time ramp investment, then calculate contribution from collected jobs. The model below distinguishes economic break-even from cash runway—a distinction that matters when manager time is allocated rather than newly paid.
Break-even realized jobs = fixed monthly seat cost ÷ sales contribution per realized job. Round up only when deciding how many whole completed and collected jobs are required. Keep one-time hiring cost separate from the monthly numerator; use the surplus after fixed cost to evaluate payback.
Hire another rep or repair the work already available?
Use the illustrative base model below: $6,700 fixed monthly seat cost, about $4,055 contribution per installed and collected job and $5,800 one-time hiring/ramp cost. Those amounts are planning inputs, not national roofing pay averages. A whole-job break-even of two does not mean two jobs repay the hiring investment.
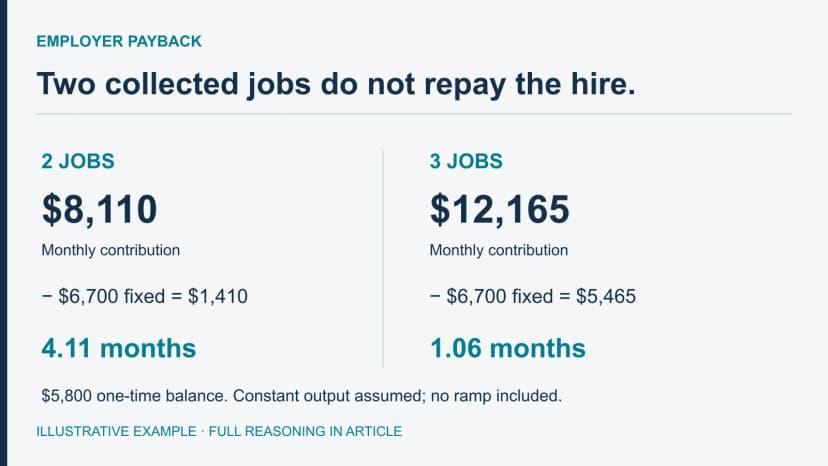
Hire case: At two realized jobs, monthly contribution is $8,110. Subtract $6,700 fixed cost and $1,410 remains. The $5,800 one-time balance would take about 4.11 equally productive months to recover, before any ramp shortfall. At three realized jobs, $12,165 contribution leaves $5,465, and the same balance takes about 1.06 months. Those are mathematical payback scenarios, not a promised hiring schedule.
Capacity check: Suppose a new rep is expected to receive ten held appointments and the company's observed collected-job yield is 20%. That supports two expected realized jobs, not ten. If there are only five incremental held appointments after redistributing existing work, expected output falls to one job: $4,055 minus $6,700 = a $2,645 recurring shortfall. Do not count appointments transferred away from another rep as new company demand.
Repair case: A proposed $1,500 workflow repair could recover missed existing appointments. If it produces one additional realized job with the same contribution and no displaced work, the model yields $2,555 net contribution. If it recovers only a signature that has not yet been installed and collected, the contribution remains unverified. The repair wins this illustrative comparison only after its incremental economics are supported.
Decision record: Finance verifies fixed cost; sales operations verifies incremental appointments; job costing verifies contribution; the manager verifies support capacity. Hire when those inputs support another seat. Repair routing or follow-up first when existing work is being lost upstream.
The model includes allocated manager time as well as cash. Track recoverable draws separately from commission. Payroll and classification questions need qualified review.
Related guidance: roofing sales rep earnings, worker-classification guide, sales margin calculator.
Define “Realized Job” Before You Calculate Cost
Use a consistent job milestone. This model uses installed and collected work. If management reports completed-and-collectible jobs, reconcile receivables separately; do not mix that denominator with collected jobs.
Start with collected revenue minus direct job cost. Subtract variable sales costs once to obtain contribution. Do not use contract revenue in place of contribution or subtract commission already included in job cost.
Sales contribution per realized job = collected revenue − direct job cost − variable commission − employer payroll tax on variable pay − attributable lead cost − other measured variable sales cost.
The SBA’s break-even guidance separates fixed and variable costs. Here, the unit is one realized roofing job and the company supplies the costs.
One Rep, Four Ledgers
A single “fully loaded percentage” hides the timing and ownership of cost. Keep four ledgers for each hiring cohort, then reconcile them monthly. This is the core of the model.
- Compensation ledger: use the payroll register, commission statement, and signed plan to separate nonrecoverable base or guarantee, recoverable draw balance, earned commission, bonus, and SPIFF. It answers what was earned, advanced, or still recoverable.
- Employer-burden ledger: use payroll reports, state accounts, carrier invoices, and benefit invoices for employer FICA, FUTA/SUTA, workers' compensation, benefits, overtime, and reimbursements. It answers what the employer incurred above stated cash pay.
- Seat-and-ramp ledger: use the general ledger, vendor invoices, time logs, and lead ledger for recruiting, onboarding, CRM, phone, vehicle, manager hours, training setup, and starter opportunities. It answers what opening and supporting the seat consumed.
- Realized-job ledger: join the CRM cohort ID to collected revenue, actual direct job cost, variable sales pay, lead cost, discounts, credits, and callbacks. It answers what contribution the rep's completed and collected work produced.
Use the ledgers to identify why payback changed: margin, collection timing, lead cost, support hours or pay-plan treatment. Employee earnings and employer cost are different totals.
Classify Every Input Before Adding It
Every line belongs in one of four calculation buckets. If the team cannot classify a line, it should not disappear into “other” or a vague waste reserve.
- One-time hiring and ramp cost: recruiting, screening, account setup, initial training, and dedicated onboarding hours. Track separately; if management amortizes them, disclose the period instead of calling all of it recurring monthly cost.
- Fixed monthly seat cost: guaranteed base, fixed tools, vehicle allowance, benefits, and allocated manager capacity. This is the monthly break-even numerator; do not add variable commission at assumed volume.
- Variable cost per realized job: commission, employer tax on variable pay, source-attributable lead cost, and job-variable mileage. Subtract these from realized gross profit once to calculate contribution.
- Timing or contingency: cancellation, completion, collection, chargeback, draw recovery, and replacement risk. Model them with observed rates or labeled low, base, and high cases—not an unsupported “waste reserve.”
Value manager hours, but label the result. Twelve hours of an existing manager’s time may displace pipeline review without adding payroll. Keep that allocation in the economic model and out of incremental cash spending.
If callbacks, discounts or rework are already in job cost, do not add a second “production drag” line. Otherwise, record the measured correction against its job.
Use Actual 2026 W-2 Burden Inputs
Wages are not total employer cost. BLS compensation data and its occupation and industry table distinguish wages and benefits across groups; neither provides a roofing-sales payroll multiplier. Use your company’s actual costs below.
Build the W-2 burden from actual line items:
- Employer Social Security: 6.2% of taxable wages up to the 2026 wage base of $184,500.
- Employer Medicare: 1.45% of taxable wages, with no wage cap. Additional Medicare tax is employee withholding; there is no employer match.
- Federal and state unemployment: use the employer's actual federal credit status, state rate, and wage base. The 2026 IRS Publication 15 explains federal payroll inputs; state rates vary.
- Workers' compensation: use the carrier's assigned classification and payroll basis. A rep who inspects or accesses roofs may not price like a desk-only sales role. The Department of Labor's state workers' compensation directory points to the responsible state programs.
- Benefits and paid time: use actual invoices and policy costs. Avoid counting paid leave twice when salary already continues during leave.
- Vehicle: use either documented personal-vehicle reimbursement or a company-vehicle cost model—not both.
The optional IRS business-mileage rate changed during 2026: 72.5 cents per mile for January through June and 76 cents beginning July 1, according to the IRS mileage table. That is a tax and substantiation rate, not a universal federal reimbursement requirement and not proof of the company's actual vehicle cost.
Do not count employee federal income-tax withholding or the employee share of FICA as added employer expense. The employer withholds and remits those amounts, but the expense model should distinguish withholding responsibility from employer-funded tax.
Worked Example: A Corrected Employer Model
The following numbers are illustrative assumptions, not roofing benchmarks. The example models a W-2 rep with a nonrecoverable base and variable commission. It assumes commission is not already included in direct job cost.
| Line | Illustrative amount | Classification | Replacement record |
|---|---|---|---|
| Nonrecoverable base | $3,500 per month | Fixed monthly | Payroll register and signed plan |
| Employer Social Security and Medicare on base | $268 | Fixed monthly | Payroll tax report; example uses 7.65% |
| Benefits, UI, and workers' compensation | $782 | Fixed monthly placeholder | Actual benefit, state, payroll, and carrier records |
| CRM, phone, proposal, and measurement tools | $300 | Fixed monthly | Allocated vendor invoices |
| Fixed vehicle or allowance cost | $450 | Fixed monthly | Company policy and expense report |
| Manager capacity allocation | $1,200 | Fixed monthly allocation | 12 measured hours × $100 documented loaded allocation |
| Recurring administration | $200 | Fixed monthly | Measured payroll or service allocation |
| Fixed monthly seat cost | $6,700 | Break-even numerator | Reconcile monthly |
| Recruiting and screening | $1,300 | One-time illustration | Invoices plus interview-hour allocation |
| Setup and onboarding administration | $300 | One-time illustration | Invoices and payroll |
| Dedicated onboarding and ride-along time | $2,400 | One-time illustration | Measured hours × documented allocation |
| Starter-opportunity acquisition spend | $1,800 | One-time illustration | Lead-source ledger |
| One-time hiring and ramp cost | $5,800 | Economic payback balance | Keep separate from monthly break-even |
The $1,800 starter-acquisition line and the $450 per-job acquisition cost must cover different spending. This illustration treats starter spend as a separate launch cohort. If the realized jobs came from that same funded pool, reconcile the shared spend once rather than charge both lines.
Now calculate one realized job. Assume $18,000 in collected revenue and $11,700 in actual direct job cost, producing $6,300 in gross profit before sales cost. Subtract $1,575 of variable commission, $120 of employer Social Security and Medicare on that commission, $450 of attributable lead cost, and $100 of variable mileage. The resulting contribution is $4,055.
$18,000 − $11,700 − $1,575 − $120 − $450 − $100 = $4,055 contribution per realized job.
Monthly break-even is $6,700 ÷ $4,055 = 1.65 realized jobs, so the operating threshold is two completed and collected jobs. At exactly two jobs, monthly contribution after fixed seat cost is $8,110 − $6,700 = $1,410. The rep is above recurring monthly break-even, but the original $5,800 ramp balance has not yet been recovered.
At two realized jobs, the $1,410 surplus takes about 4.1 equally productive months to recover the $5,800 economic ramp cost. At three, $5,465 surplus takes about 1.1 months. These are cost-payback scenarios, not a hiring schedule or a bank-cash forecast.
Stress-Test Contribution, Not Motivation
A single case creates false confidence. Use low, base, and high operating cases based on actual variations in collected job size, direct cost, commission, acquisition cost, and travel. The table below is a stress test—not a forecast or confidence interval.
| Input | Low contribution | Base | High contribution |
|---|---|---|---|
| Collected revenue per realized job | $16,000 | $18,000 | $20,000 |
| Direct job cost | $10,400 | $11,700 | $12,400 |
| Variable commission | $1,400 | $1,575 | $1,900 |
| Employer FICA on commission | $107 | $120 | $145 |
| Attributable lead cost | $650 | $450 | $350 |
| Variable mileage | $125 | $100 | $75 |
| Contribution per realized job | $3,318 | $4,055 | $5,130 |
| Exact break-even jobs | 2.02 | 1.65 | 1.31 |
| Whole realized jobs required | 3 | 2 | 2 |
Build the cases from trailing realized jobs by lead source and work type. Do not use the largest projects a top rep remembers. If the company sells retail replacements, repairs, insurance-related work, and commercial work, keep separate cohorts when their margins and collection timing differ.
Separate Cash Runway from Economic Cost
First separate cash spending from existing capacity allocations. In this illustration, assume the $1,200 monthly manager allocation and $2,400 one-time onboarding allocation use existing salaried capacity and add no payroll. Assume the remaining entries are incremental cash. That gives $5,500 fixed monthly cash spending and $3,400 initial cash outlay, while the economic model remains $6,700 and $5,800. Verify those assumptions against actual invoices and payroll.
- Before start: initial cash exposure is −$3,400.
- Month 1: no collected jobs minus $5,500 cash spending leaves −$8,900 cumulative cash exposure.
- Month 2: one job contributes $4,055, leaving a −$1,445 cash shortfall and −$10,345 cumulative exposure.
- Month 3: two jobs contribute $8,110, leaving +$2,610 cash surplus and −$7,735 cumulative exposure.
The same sequence including capacity allocations has −$13,735 cumulative economic exposure. Keep both totals: cash measures funding need; economic cost measures the resources consumed. If the hire requires manager overtime or a replacement trainer, move that incremental payment into cash.
This is a simplified seat-contribution sequence, not a full bank forecast. Map actual dates for customer deposits, production payments, commission and collection separately. One collected job can replenish cash after the company has already paid its crew and supplier.
Treat Each Pay Plan According to Its Economics
- Salary or nonrecoverable guarantee plus commission: treat the guarantee as fixed and commission plus employer tax on it as variable. The written plan must define when commission is earned, paid, adjusted, or charged back under applicable law.
- Recoverable draw against commission: track the cash advance and draw balance without counting it again as final commission expense. Define what can lawfully be recovered, from which earnings, and what happens at separation.
- Commission-only W-2: commission is variable, but employer taxes, unemployment insurance, workers' compensation, tools, leads, management, and possible overtime remain. Verify exemption and wage-rule treatment.
- Properly classified independent contractor: track contract payments, agreed reimbursements, company-provided tools and leads, vendor administration, and management burden. The facts must satisfy every applicable federal and state test.
The IRS classification guidance examines control and the working relationship. A W-9 or contract label does not decide status, and wage-and-hour or state tests may differ.
Check the DOL’s 2026 rulemaking page and current requirements with qualified counsel. Do not treat proposed rules as effective law.
Commission does not by itself remove overtime obligations. The DOL’s outside-sales guidance addresses duties and work location; its regular-rate guidance explains commissions in overtime calculations. Have payroll and counsel review the actual role and state rules.
Measure Lead Source and Manager Time Without a Waste Reserve
Keep source attached from intake to collection. For paid demand, divide net cohort spend by its realized jobs; for canvassing, allocate paid field time and attributable travel. Use the lead cost calculator for the full acquisition model.
- Paid search or marketplace leads: track speed to contact, valid contact, held appointment, realized job, and source spend.
- Referrals: track the referral program cost and trust risk; “free” is not automatically zero-cost.
- Door knocking: track paid field time, territory, contacts, appointments, and realized jobs rather than assigning a generic lead value.
- Aged estimates: retain original acquisition cost and measure the incremental reactivation work separately.
- Insurance or storm work: keep completion and collection timing visible; a signature can be far from realized contribution.
If the company uses lead-release gates, document the observed behaviors and apply them consistently. Do not call practice completion proof of sales readiness.
Use the training cost model for program economics and the turnover model for replacement losses. Keep those costs distinct from the active seat.
Run the Double-Count Audit
Before presenting the result, have the bookkeeper, sales leader, and operations leader challenge these seven points:
- Commission: Is variable commission excluded from direct job cost? If it is already included, do not subtract it again.
- Recoverable draw: Is the draw tracked as an advance and balance, or was it counted as both base pay and commission?
- Lead cost: Is total source spend already divided into cost per realized job? If yes, remove any second “lead waste” reserve.
- Production correction: Are discounts, credits, callbacks, or rework already in actual job cost?
- Overhead: Is the same overhead allocated to the job and the monthly seat?
- Manager time: Is it incremental payroll cash, a capacity allocation, or an opportunity cost? Do not label one as another.
- Tax and benefits: Are actual employer-paid amounts separated from employee withholding and salary already paid during leave?
A corrected model should reconcile back to the general ledger, payroll, job-cost report, and CRM cohort. If it cannot, treat the answer as a planning scenario rather than an accounting result.
Use Evidence-Based Continue, Reset, and Exit Gates
Set review criteria before hiring. Job cycles, lead sources and manager support change ramp economics; an elapsed day count does not identify the right employment decision.
- Continue: required behaviors are improving, manager rescue time is falling, opportunity records are complete, realized contribution is moving toward the predeclared case, and the cash runway still supports the plan.
- Reset: a specific constraint is identifiable and coachable—for example, lead routing, estimate explanation, follow-up ownership, handoff completeness, or an unrealistic territory—and a documented corrective plan has an owner and review date.
- Exit or reassign: repeated material failures remain after communicated expectations, support, and a fair review; the economics no longer fit the approved runway; and the decision follows company policy and applicable law.
This model should support a decision, not automate a consequential employment action. Managers should examine source quality, training quality, territory, capacity, and process failures before attributing every variance to the worker.
What to Do Before You Open the Seat
- Set the job economics. Confirm collected revenue, direct job cost, and realized gross profit by work type and source.
- Write the compensation treatment. Use the sales commission plan builder, then have payroll and counsel review earning events, draws, deductions, chargebacks, and final pay.
- Reserve manager capacity. Put onboarding, ride-along, review, and handoff hours on the calendar instead of hiding them inside goodwill.
- Model team capacity. Use the roofing sales team capacity calculator so appointment volume and production capacity can support another seat.
- Define the ramp evidence. Use the sales onboarding plan to set role-specific milestones, lead-release gates, and review dates.
- Build the runway. Approve one-time cash, monthly fixed cost, low/base/high contribution cases, and a stop-review date before recruiting begins.
GhostRep's role is bounded: GhostRep is designed to help roofing teams run roleplay, capture readiness evidence, and inspect coaching work before or alongside live opportunities. It does not determine classification, payroll burden, commission legality, job margin, or whether a person should be hired, disciplined, or terminated.
For the broader contractor workflow around practice, field conversations, coaching, and management review, see the GhostRep roofing solution.
Source Notes
Source review: September 28, 2026. IRS mileage inputs were rechecked; BLS figures remain context rather than a company burden estimate. State payroll, commission, reimbursement, classification and workers’ compensation requirements need qualified review. All roofing dollar figures here are assumptions to replace with payroll, invoices, job costs, CRM cohorts and receivables.
Frequently Asked Questions
What is the average cost of a roofing sales rep?
There is no reliable universal average that combines roofing pay plans, employer taxes, state programs, benefits, vehicles, tools, lead sources, manager time, ramp length, and realized job margin. Calculate one-time ramp cost, fixed monthly seat cost, and variable cost per realized job from company records. Use external averages only as context, not as the answer.
How do you calculate roofing sales rep break-even jobs?
Divide fixed monthly seat cost by contribution per completed and collected job. Contribution is collected revenue minus direct job cost, variable commission, employer payroll tax on variable pay, attributable lead cost, and other measured variable sales cost. Round the result up to the next whole realized job for an operating threshold.
Should base pay, commission, and a draw all go into monthly cost?
Not automatically. A nonrecoverable base or guarantee is usually fixed. Commission is normally variable with production. A recoverable draw is an advance against future commission and needs its own cash balance so it is not counted again as final commission expense. The signed plan and applicable law determine the actual treatment.
Should break-even use signed, installed, or collected jobs?
Use the milestone that matches the company's realized economics and apply it consistently. Installed and collected is conservative because it excludes cancellations and unresolved receivables. If management uses completed-and-collectible work, keep a separate collection reconciliation and never mix the definitions between periods.
Is a 1099 roofing sales rep automatically cheaper than a W-2 rep?
No. Classification is fact-specific, not a cost switch. A properly classified contractor may change the payroll-tax model, but contract payments, reimbursements, company-supplied tools or leads, administration, insurance requirements, and management burden remain. Federal tax, wage-and-hour, and state tests can differ.
Should manager coaching time count as rep cost?
Yes, when it is measured and labeled correctly. It may be incremental cash, allocated capacity, or opportunity cost depending on the manager's pay and workload. Record hours and a documented loaded allocation, then state which type of cost it represents.
What is the difference between monthly break-even and payback?
Monthly break-even occurs when realized-job contribution covers recurring fixed seat cost for that period. Payback occurs later, when cumulative contribution also recovers recruiting, onboarding, earlier monthly losses, and other approved ramp costs. A rep can be monthly-break-even positive while cumulative exposure is still negative.
About the Author
Tim Nussbeck
Founder & CEO of GhostRep
20+ years in roofing and home improvement sales—knocking doors, running teams, and building practical coaching systems. Built GhostRep to give every rep access to the coaching top teams get.
Hiring next step
Turn hiring advice into a documented human process
Start with free hiring resources if you need job descriptions, structured interview worksheets, or onboarding docs. GhostRep's standard product walkthrough begins with post-hire onboarding, practice, and coaching.
- ✓Best fit if managers are wasting time on low-signal interviews.
- ✓Useful for job-related evidence notes, interview structure, and onboarding clarity.
- ✓Use consistent job-related questions and keep every employment decision with a human reviewer.
Start Here
Browse hiring tools
Generate evidence worksheets, structured questions, onboarding plans, and accountability docs.
Browse hiring toolsNeed it mapped to your team?
Talk through your current workflow, traffic mix, and where GhostRep fits before you change anything.
Book a 15-minute walkthroughYou Might Also Like
BLS puts the roofing sales rep median at $71,310, middle half $50,390 to $98,910. See published employer offers, commission math and first-year worksheet.
Read article →Compare W2 employees and 1099 contractors for roofing sales using current IRS and DOL factors, operating costs, and a manager fact checklist.
Read article →Compare current training with an AI-supported workflow using consistent costs, manager time and observed outcomes. Includes a worked cost model.
Read article →